Key Takeaways
- Understanding prescription drug coverage options helps you plan confidently for healthcare needs in retirement.
- Regularly reviewing your coverage and separating myths from facts are key to managing costs and securing the right support.
Most adults age 65 and older take prescription medications—yet many face confusion about how prescription drug coverage works in retirement. Gaining clarity on the fundamentals can help you make informed decisions and avoid common pitfalls as your medical needs evolve.
What Is Prescription Drug Coverage?
Definition and basic concepts
Prescription drug coverage is a type of health protection that helps pay for the cost of physician-prescribed medications. This coverage reduces your personal spending on prescription drugs by spreading the risk and cost across larger pools of people, often organized through private health plans or government programs. The main goal is to make necessary medicines more accessible and affordable—especially important as you age and medical needs increase.
Types of drug coverage in retirement
When you retire, your sources of coverage may change from employer-based plans to alternatives such as:
- Government-sponsored coverage (commonly through national programs designed for retirees)
- Traditional group health plans (sometimes available to retirees from past employers)
- Supplemental options that can be paired with base coverage to address additional needs or fill in gaps
Each approach functions differently in terms of coverage breadth, cost structure, and eligibility, making it important to understand what’s available and how it might fit your specific situation.
Why Does Prescription Coverage Matter?
Health and financial impacts
Prescription medicines are often critical for managing chronic conditions or preventing more serious health issues as you age. Without proper coverage, you might face significant out-of-pocket expenses—sometimes high enough to limit your ability to adhere to treatment. Insurance protections serve as a safety net, preserving both your health and your financial security over time.
Changing needs as you age
Your prescription requirements are likely to shift as you get older. Certain medications may become necessary that were not needed previously, and changes in your health status could alter the number, type, and cost of prescriptions you require. Ensuring you have flexible and sufficient coverage can help you adapt without experiencing financial strain or gaps in care.
What Are Your Coverage Options?
Traditional health plans
Some retirees may continue coverage through employer-sponsored group health plans, though access may diminish after leaving the workforce. These plans may offer prescription coverage as an integrated part of overall health benefits. Understanding the specifics—such as which medications are covered and how costs are shared—is essential if you retain this option.
Government programs
Government-provided options are a cornerstone for many retirees. These programs often include dedicated prescription coverage, which you may need to enroll in separately from other healthcare benefits. Coverage typically involves a list of approved medications (known as a formulary), cost-sharing features, and rules about where you can fill prescriptions. Thoroughly reviewing eligibility and enrollment periods helps ensure you don’t miss opportunities to secure this protection.
Supplemental solutions
In addition to core plans, you might explore supplemental options. These can be standalone plans or additions that work alongside basic coverage, reducing your share of costs for certain medicines or expanding the range of covered drugs. Supplemental solutions often respond to unique healthcare needs or fill gaps in existing coverage, offering increased flexibility as your situation changes.
How Are Prescription Costs Determined?
Factors affecting drug expenses
Several variables shape what you pay for prescription medications in retirement, including:
- Type of medication: Generic versus brand-name drugs tend to have different prices.
- Coverage structure: Whether a drug is included in your plan’s formulary affects your share of payment.
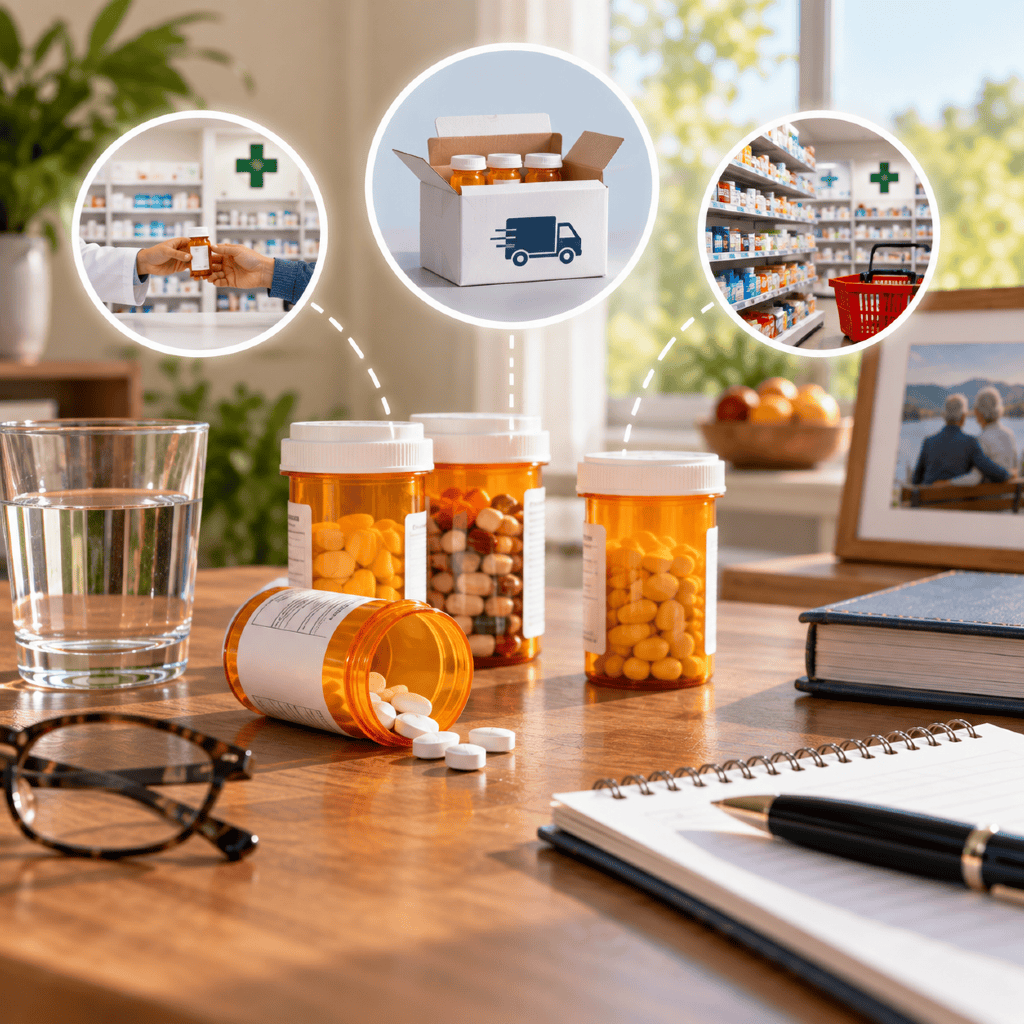
- Pharmacy network: Where you fill your prescription matters; in-network pharmacies may result in lower costs.
- Tiered systems: Many plans group drugs into cost tiers, with lower tiers generally costing you less out of pocket.
- Annual deductibles, coinsurance, and copayments: These features influence your portion of the cost and can change year to year.
Common out-of-pocket scenarios
You may encounter a variety of out-of-pocket situations:
- Filling non-formulary prescriptions might mean you pay the full price.
- If you switch pharmacies, using an out-of-network location can increase your expenses.
- Reaching certain cost thresholds can shift which portion of expenses you and the plan each pay, with some coverage types featuring specific coverage “gaps.”
Understanding these scenarios encourages proactive planning and helps limit surprises when accessing your medications.
What Are Common Coverage Misconceptions?
Myths about eligibility
It’s common to mistakenly assume that all retirees are automatically eligible for certain prescription plans, or that enrollment is unnecessary unless you have immediate needs. In reality, eligibility criteria and enrollment periods can vary substantially. Failing to enroll on time or assuming automatic coverage can result in penalties or unintended gaps in protection.
Assumptions about costs
Another widespread misconception is that all prescription costs are fully covered with a plan. Most coverage involves some cost-sharing, whether through co-payments, deductibles, or a limited formulary. It’s important not to overestimate what’s included—and to budget for out-of-pocket expenses that may still occur. Informed planning leads to fewer unpleasant surprises.
How Can You Review Coverage Annually?
Factors to consider during review
Annual review ensures your prescription coverage aligns with your evolving medical needs. Key considerations include:
- Have your prescriptions changed, requiring different formulations or drugs?
- Have costs or plan features been updated since last year?
- Are your preferred pharmacies still in network?
- Does your plan’s formulary now omit any drugs you need?
Regular check-ins help you identify opportunities for savings or improved protection.
Resources for staying informed
Staying up to date is easier when you use reliable informational resources. These may include official government health program websites, benefit summary documents sent out annually, and unbiased educational guides from trusted organizations. Engaging with these resources allows you to make decisions based on current, accurate information, rather than assumptions or outdated knowledge.