Key Takeaways
- Pensions may offer dependable income, while lump-sum payouts provide flexibility but introduce risk and planning complexity.
- Inflation, market movement, and future needs all influence which retirement option fits your circumstances best.
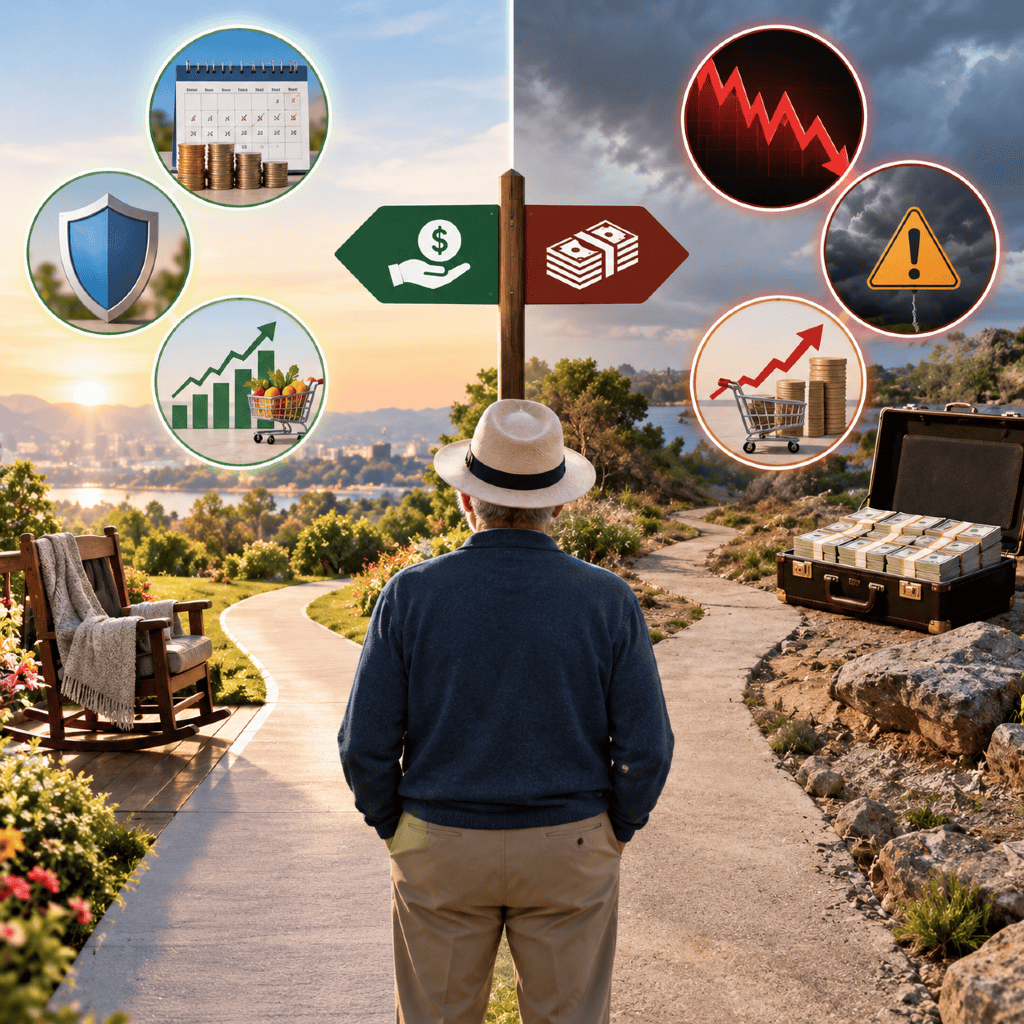
Facing the choice between a pension and a lump-sum payout is a pivotal part of retirement planning. Understanding how income stability, risk factors, and inflation affect each route can empower you to make an informed, confident decision as you transition into retirement.
What Is the Pension vs Lump-Sum Decision?
Definitions of pension and lump-sum
A pension typically provides you with a guaranteed stream of regular payments throughout retirement. These payments often last for life, offering predictability. By contrast, a lump-sum option allows you to receive the present value of your pension as a single payout, which you then manage or invest yourself. The pension route hands off the responsibility of managing money to the pension plan, while the lump-sum grants you direct control over the assets but also the associated obligations.
Common scenarios for each option
You might encounter this decision at retirement, when leaving an employer, or during organizational changes. Some individuals prefer the structure and stability of a traditional pension, especially if they value regular, steady income. Others lean toward the lump-sum if they seek greater investment flexibility, have legacy goals, or wish to manage their funds more actively. Each scenario brings different considerations to weigh, based on your unique goals and financial circumstances.
Which Option Provides Greater Income Stability?
How regular payments differ
Opting for a pension usually means receiving a predictable monthly amount for life or for a set period, mirroring a steady paycheck. This regularity simplifies budgeting and lends peace of mind, knowing that income arrives automatically each month. Choosing a lump-sum, on the other hand, places responsibility on you to withdraw funds prudently. Without careful planning, withdrawal rates can be difficult to maintain, and income may fluctuate based on market performance or spending variations.
Longevity and predictability of income
A pension’s structure is designed to last as long as you live, providing a systematic solution to longevity risk—the chance that you might outlive your savings. With a lump-sum, you must plan withdrawals carefully to mitigate this risk. The longevity of your income depends on investment returns, withdrawal decisions, and market behavior. While the pension option centralizes and streamlines longevity protection, lump-sum decisions demand continuous adjustment to remain sustainable over time.
What Risks Are Involved?
Potential for market and sequence risk
Taking a lump-sum introduces direct exposure to market risk—the possibility that investment losses could reduce the available principal over time. Sequence risk also comes into play; this is the risk of experiencing poor investment returns, especially early in retirement, which can accelerate depletion of the portfolio. Pension plans buffer you from these market swings, insulating your monthly income from most short-term investment fluctuations.
Longevity and benefit security considerations
With a pension, the security of your payments depends partly on the funding health and management of the plan. While protections exist in many systems, changes in pension plan health can raise concerns about benefit security. Lump-sum recipients sidestep plan solvency risk but need to plan for their own longevity risk—a complex task involving variables like life expectancy, health, and investment outcomes. Both routes carry distinct uncertainties, but the nature and source of the risk differ significantly.
How Does Inflation Affect Each Option?
Loss of purchasing power over time
Inflation gradually erodes the purchasing power of fixed payments. Most traditional pensions provide set monthly benefits that rarely adjust meaningfully for inflation, meaning that your starting pension may cover less as years pass. In contrast, a lump-sum payout, if managed with growth in mind, has the potential—though not a guarantee—to generate returns that may keep pace with, or even surpass, inflation over time. However, this depends on investment choices and market conditions.
Options to address inflation risk
Some pension designs include cost-of-living adjustments (COLAs), which help offset inflation, but many do not. As a lump-sum recipient, you have the potential to select investments that provide some hedge against inflation, such as certain equities or inflation-protected securities. This introduces added complexity, as decisions about asset allocation and risk management become critical for preserving long-term purchasing power.
Key Considerations Beyond the Top Three
Flexibility and control of funds
The lump-sum approach offers maximum flexibility: you can decide where the assets are held, how they are invested, and when distributions occur. This flexibility can support evolving needs or goals, but it also demands careful oversight and disciplined financial management. Pension payments, by contrast, offer limited flexibility—they deliver fixed income on a set schedule, which simplifies management but can’t be readily adjusted for changing life situations.
Estate planning implications
A lump-sum payout may fit well with specific estate planning objectives. You retain the ability to direct remaining assets to heirs or charities if your account has value at the time of your death. Pensions, on the other hand, may reduce or end payments after your passing, though there are sometimes options for beneficiary or survivor benefits. The impact on your legacy should be part of your broader financial considerations when evaluating these retirement choices.