Key Takeaways
- Vesting schedules determine when you fully own employer contributions in retirement plans.
- Understanding these timelines helps you make informed decisions about your retirement savings and job moves.
Retirement planning depends on more than how much you save—it’s also shaped by when and how you gain ownership of your employer’s contributions. Vesting schedules are powerful yet often overlooked rules that set the timeline for when you gain rights to those funds. This guide unpacks vesting schedules, their types, and their impact on your retirement planning.
What Are Vesting Schedules?
Basic vesting schedule definition
A vesting schedule is a timeline an employer sets to determine when you become the full legal owner of contributions made to your retirement plan on your behalf. While the money you personally contribute is typically always yours (called “immediately vested”), employer contributions become fully yours according to specific rules—the vesting schedule. Until you’re vested, you could forfeit some or all of those funds if you leave your employer.
Why vesting exists in retirement planning
Vesting schedules aren’t arbitrary. They’re designed to encourage long-term employment and help employers manage benefit costs. By tying full ownership of contributions to a set period of service, employers incentivize you to stay longer and offer a clear retirement benefit over time.
Why Does Vesting Matter for Retirement?
Long-term benefit protection
Vesting schedules protect long-term benefits for both employees and employers. For you, your vesting status determines what you can take with you if you switch jobs. For employers, vesting helps ensure that retirement benefits serve as both a reward for tenure and a retention tool.
Influence on saving strategy
Knowing your vesting timeline helps you make smarter savings choices. If you’re not yet fully vested, it might influence whether you stay with your employer or how you think about rolling over funds. Knowing your schedule helps you avoid potential forfeitures and plan your retirement contribution strategy around your timeline for full ownership.
What Types of Vesting Schedules Exist?
Cliff vesting explained
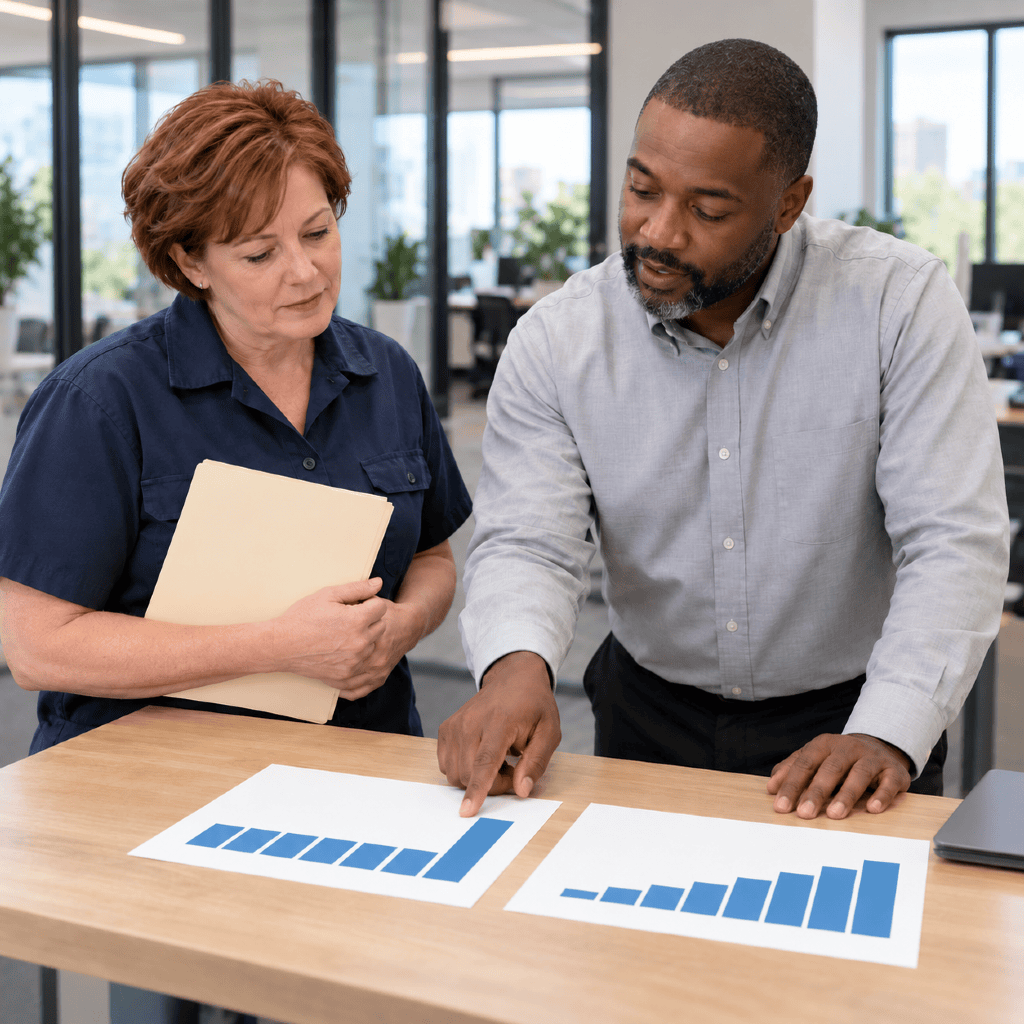
With cliff vesting, you gain full ownership of your employer’s contributions all at once after completing a set period of service, such as three years. Before this period, you have no ownership over the contributions. Once you reach the cliff, you become 100% vested instantly in those employer-provided funds.
Graded vesting overview
Graded vesting lets you earn a percentage of employer contributions each year over a set period. For example, you might be vested at 20% after two years, increasing annually until reaching full ownership by year six. This gradual path means you don’t have to wait several years for any employer-contributed funds to become yours—the vesting accumulates over time.
Immediate vesting concept
With immediate vesting, you own all employer contributions as soon as they’re added to your retirement plan. There’s no waiting period. This schedule provides maximum benefit flexibility, letting you take the full value with you regardless of tenure, though it’s less common in many employer-provided retirement plans.
How Do Schedules Affect Your Benefits?
Determining ownership over time
The type of vesting schedule your plan uses dictates the pace at which employer contributions become nonforfeitable. If you leave the employer before you are fully vested, you may only be entitled to take the portion that is vested according to the schedule. The rest usually reverts back to the plan or sponsor. Knowing your vesting timeline is critical to understanding what portion of your benefits you’ll keep.
Impact on withdrawals and rollovers
Your vested balance is what you’re eligible to roll over to another retirement account or withdraw (subject to plan and regulatory rules) when leaving your job. Unvested employer contributions are typically not portable if you exit before full vesting. Recognizing this limitation can help you plan job changes and manage your retirement account.
Vesting and Job Changes: What Happens?
Portability of retirement benefits
When you change employers, only the vested portion of your retirement account typically moves with you. This means you can roll over your contributions and any vested employer contributions into a new retirement plan or an individual retirement account (IRA), helping your retirement savings keep growing even as you change jobs.
Forfeiture and plan terms
You usually forfeit unvested employer contributions if you leave before you meet the schedule’s requirements, meaning you’ll lose access to those funds. However, the specifics depend on your plan’s legal terms. Some plans may allow accelerated vesting under certain situations (such as retirement or plan termination), but these options are governed by plan documents and regulations.
Pros and Cons of Each Vesting Type
Advantages of different schedules
- Cliff vesting: Employees who meet the required service period receive the full benefit at once, which can feel rewarding and substantial.
- Graded vesting: Provides partial access earlier, reducing the “all-or-nothing” risk and offering more flexibility as tenure accumulates.
- Immediate vesting: Maximizes flexibility, making every employer contribution portable regardless of service length.
Potential limitations
Every schedule has trade-offs:
- Cliff vesting can be risky if you anticipate leaving before the service requirement—it’s possible to lose all employer contributions.
- Graded vesting means you earn ownership gradually, which can reduce the benefit if you change jobs often.
- Immediate vesting is uncommon because it may reduce employers’ incentive to retain employees.
Understanding these factors helps you align career moves with your retirement financial goals.