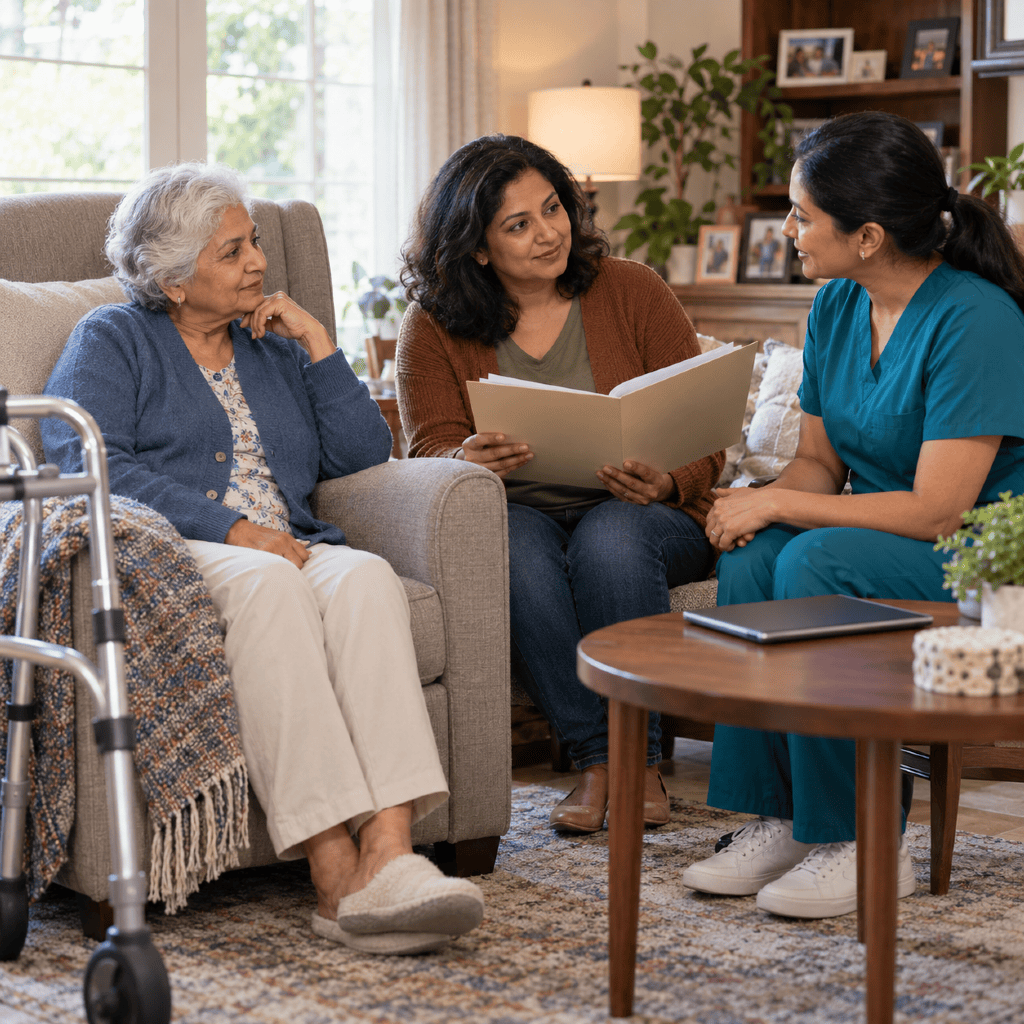
Key Takeaways
- Long-term care planning involves proactive steps to prepare for potential health, housing, and support needs later in life.
- Effective strategies include personal savings, public programs, family involvement, and legal tools—each of which should be reviewed periodically as needs change.
As life expectancy increases, preparing for potential long-term care needs becomes an important part of your retirement plan. Yet, many people underestimate both the financial impact and the practical considerations. Understanding costs, strategies, and misconceptions can help you make informed, confident decisions about your future well-being.
What Is Long-Term Care Planning?
Definition of long-term care
Long-term care refers to a wide range of services that help individuals manage daily activities because of chronic illness, disability, or advanced age. This can include help with bathing, dressing, eating, mobility, household chores, and managing medications. These services may be provided at home, in assisted living, or in specialized care facilities.
When planning becomes important
You may not think about long-term care until a sudden health event occurs, but advanced planning offers significant advantages. Ideally, you should begin considering your future care needs as part of your wider retirement strategy—typically once you are in your fifties or sixties. Early planning gives you more time to align resources, involve family, and ensure that your preferences are respected.
Why Does Long-Term Care Cost So Much?
Types of care and settings
Long-term care services span a spectrum, from in-home care to community services, assisted living, and skilled nursing facilities. Each type varies in scope, setting, and intensity:
- In-home care: Aides or nurses help with personal care and medical tasks at home.
- Community services: Day programs, meal services, and transportation provide support for those living independently.
- Assisted living: Facilities offer residential support for those needing some assistance but not constant supervision.
- Skilled nursing: These facilities provide both medical care and daily living support for individuals with higher needs.
Common cost drivers
Several factors drive long-term care costs. Key factors include the level and duration of care needed, the setting (in-home vs. facility-based), geographic location, and the availability of trained staff. Those who need complex, around-the-clock support or medical supervision can expect higher costs. Additionally, healthcare inflation and staffing challenges can drive costs up over time.
What Are the Five Main Strategies?
Personal savings approach
One common approach to long-term care involves setting aside personal savings specifically for future care needs. This may include designating retirement accounts or other assets for potential use if you require support. While this strategy offers flexibility, it can heavily strain your financial resources if care needs are extensive or prolonged.
Government program options
Public programs such as Medicare and Medicaid play a role in long-term care—though they are often misunderstood. Medicare primarily covers short-term, medically necessary care, such as rehabilitation after a hospital stay, and generally does not cover extended personal or custodial care. Medicaid may cover long-term care for eligible individuals, but eligibility depends on income and assets, and the program has limits and requirements to understand.
Family involvement and support
Many people rely on family members for home-based care, ranging from help with daily tasks to coordinating professional support. While this can reduce direct expenses, it may also increase caregiver stress and place a financial burden on your loved ones. An open discussion and honest assessment of your family’s capacity can clarify how much support you can realistically provide over time.
Community and nonprofit resources
Local communities and nonprofit organizations often offer valuable resources for older adults. These may include transportation, meal services, adult daycare programs, respite care, and caregiver education. Leveraging these resources can help bridge the gap between family care and paid professional support.
Legal and estate planning tools
Preparing legal documents, such as advance healthcare directives, powers of attorney, and updated wills or trusts, establishes your care preferences and protects your interests if you become unable to make decisions. Aligning estate planning with your long-term care strategy can help protect your assets for both your needs and your intended heirs.
What Are the Top Misconceptions?
Who pays for care?
A common misconception is that government programs will automatically cover all long-term care costs. In reality, individuals and families pay most care expenses, especially for services provided at home or in assisted living settings.
Coverage misunderstandings
Many assume Medicare will pay for extended personal care, but it generally covers only short-term, medically necessary care. Understanding what is and isn’t covered can prevent surprises if you or a loved one requires ongoing support.
Assumptions about government aid
People often overestimate eligibility for public assistance or misunderstand Medicaid’s income and asset requirements. Each state administers these programs differently, and many have specific rules about eligibility and the types of care they cover.
How Should You Start Planning?
Assessing future care needs
Start by considering your health, family medical history, living situation, and lifestyle preferences. How likely are you to need support—and in what ways? While the future is uncertain, an honest assessment can clarify your priorities and what you need to plan for.
Discussing plans with family
Talk with your loved ones about your expectations and wishes. Who can provide support? Are those individuals willing and able? What outside resources might they need? Revisiting these discussions regularly helps ensure everyone is prepared and on the same page.
Documenting preferences and resources
Keep clear, up-to-date records of your care preferences, legal directives, insurance policies, and relevant financial information. Document contact details for key professionals or family members, and ensure that others know where to access this information in an emergency.
Will These Strategies Suit Everyone?
Personal considerations
Not all approaches will suit every person or household. Your health, financial circumstances, support network, and personal values should shape your long-term care strategy. What works for one person may not work for another.
Situations needing professional input
Certain scenarios—such as complex family situations, unique financial structures, or intricate health needs—may benefit from input from retirement professionals or legal experts. While general strategies provide a foundation, tailored guidance can further optimize your plan when your needs are particularly nuanced.
What If Your Situation Changes Suddenly?
Revisiting your plan
Life circumstances can shift quickly. Health changes, new family dynamics, or evolving financial realities should prompt you to review your long-term care plan. Regular check-ins ensure your decisions remain aligned with your goals and the resources available to you.
Adapting to new needs
Stay flexible and ready to adapt as circumstances change. Update your preferences, legal documents, and plans as needed. Involving trusted individuals and keeping information current can make transitions smoother and ensure your well-being remains the priority throughout your retirement journey.