Key Takeaways
- Retirement is a dynamic process with distinct phases and evolving personal, financial, and emotional needs.
- Understanding and regularly reassessing your retirement plan helps you adapt to changing circumstances and enjoy greater security.
Most people assume retirement follows a single, predictable path. In truth, the retirement journey involves multiple phases, each with its own milestones and surprises. By exploring the facts behind popular myths, you’ll be better equipped to plan and adapt throughout your retirement timeline.
What Are the Phases of Retirement?
Commonly accepted retirement stages
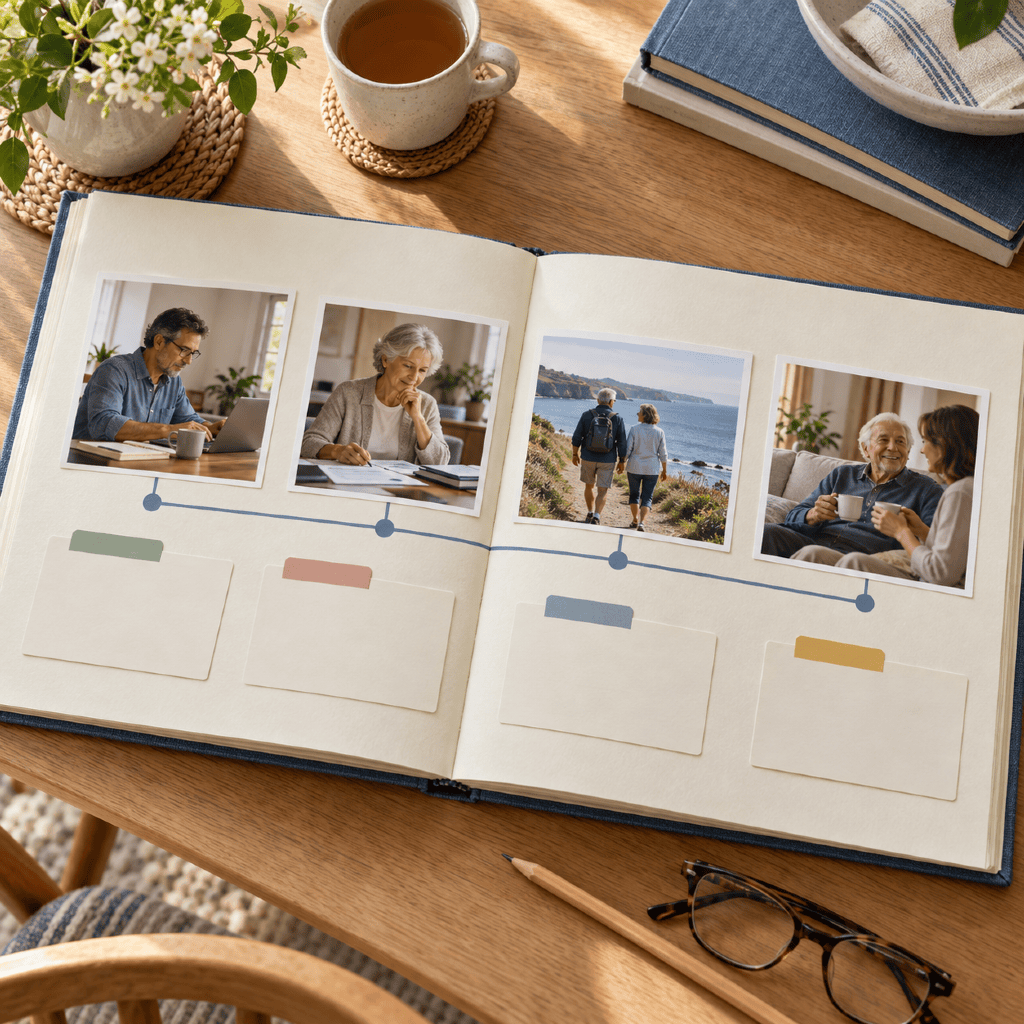
Many experts and researchers describe retirement as a series of stages, not a single event. Typically, these phases include:
- Pre-retirement: The planning and preparation years leading up to retirement
- Early retirement: The initial adjustment or transition right after leaving full-time work
- Middle retirement: A more stabilized phase when routines, spending, and lifestyle settle in
- Late retirement: A period when health, mobility, and personal needs often shift
Each stage presents its own financial and emotional considerations that can influence your planning decisions.
How the stages differ for individuals
No two journeys are identical. Your experience may differ based on your career path, health status, family structure, or life goals. Some people return to work part-time, others volunteer, or choose to relocate. Cultural background, personal interests, and social supports all shape your retirement timeline.
Why understanding these phases matters
Recognizing these stages helps you anticipate evolving needs, spot potential gaps, and stay flexible. It also highlights why a “set-it-and-forget-it” approach rarely works: retirement plans should be ongoing, not static, to reflect your changing reality.
How Do Retirement Timelines Vary?
Personal circumstances and timelines
Your retirement timeline reflects major life variables, including when you start saving, your expected retirement date, and your desired lifestyle. Individual goals, such as travel, supporting family members, or pursuing hobbies, shape your milestone moments.
Impact of health and employment status
Health events—both routine and unexpected—can accelerate or delay retirement, influence your spending, and affect your ability to work. Some choose to work beyond traditional retirement age for personal satisfaction or financial reasons. Conversely, job loss or caregiving duties can push you into retirement earlier.
Family and lifestyle factors
Family needs, such as caring for aging relatives or supporting adult children, may reshape your timeline. Marital status, spousal retirement age, and social preferences also affect when and how you move through the retirement stages.
Key Myths About Retirement Stages
Myth: There’s a one-size-fits-all phase
Many people assume everyone experiences retirement the same way, at the same pace. In reality, each person’s path is unique and shaped by many factors, including health, wealth, relationships, and unexpected events.
Myth: Planning stops after you retire
Some believe that retirement planning ends the day you stop working. However, ongoing review and adjustments are essential as needs and circumstances evolve across the retirement phases.
Myth: Expenses always decline in retirement
While some costs may decrease, such as commuting or work-related expenses, others, like healthcare, travel, or home modifications, may rise. Prepare for unexpected costs and don’t assume spending will automatically go down.
Facts About Retirement Planning Phases
Retirement planning is ongoing
Effective retirement planning isn’t a one-time task; it’s an ongoing process. Each phase—from pre-retirement to late retirement—requires new evaluations of your goals, resources, and risks.
Needs and goals shift over time
Your objectives are likely to change throughout retirement. Early phases might focus on travel and leisure, while later phases may prioritize healthcare, security, and legacy planning. Flexibility is key.
Income sources may change by phase
You may rely on different income streams at various times: workplace retirement plans, Social Security, personal savings, or part-time work. Understanding when and how these sources apply is central to building resilience across retirement stages.
What Should You Expect at Each Stage?
Pre-retirement: Planning and saving
In this stage, you’re actively saving, budgeting, and clarifying what you want out of retirement. Education about Social Security, Medicare, and tax implications is vital. This is also the time to explore which retirement lifestyle suits you best.
Early retirement: Transition period
This is when you shift from earning a paycheck to managing income flows, withdrawals, and healthcare coverage. Common themes include adjusting to new routines, making initial spending decisions, and finding new sources of purpose and connection.
Middle retirement: Stabilizing lifestyle
By now, your lifestyle typically evens out. You’ve adapted to a new schedule, continuing interests, or perhaps a new home. Budgeting for ongoing needs, monitoring your health, and refining plans become routine.
Late retirement: Changing priorities
In later stages, you may see increased health needs or consider downsizing, moving closer to family, or planning for long-term care. Priorities often shift to preserving independence, ensuring support structures, and organizing personal affairs.
How Can You Prepare for Each Stage?
Assessing your needs over time
Regularly reviewing your needs helps avoid surprises. Consider not just finances, but evolving health, housing, and family dynamics.
Adjusting plans as circumstances shift
A resilient retirement plan anticipates change. Adjust as you enter new phases—this could mean recalculating spending, shifting investments, or updating your understanding of public benefits.
Staying informed on retirement policies
Rules around Social Security, healthcare, and tax treatment evolve over time. Staying up to date allows you to make informed decisions and respond if legislation or benefits change.
Are Emotional and Social Factors Overlooked?
Role of identity and purpose
Retirement is more than a financial event—it’s an emotional milestone. Many find purpose through new hobbies, volunteering, or deepening friendships. Losing your work identity can be challenging, and planning for emotional fulfillment matters as much as financial readiness.
Staying socially connected
Connections to friends, family, and community can provide support and meaning throughout retirement. Isolation is a risk, but actively seeking social outlets—clubs, classes, volunteering—builds resilience.
Managing transitions and expectations
Transitions can be tricky, especially when plans change unexpectedly. Accepting that uncertainty is part of the process, and staying open to new experiences, helps manage expectations and reduce stress.