Key Takeaways
- Dollar-cost averaging and lump sum investing each have unique strengths and potential drawbacks in retirement planning.
- The best strategy often depends on your risk comfort, emotional tendencies, and specific retirement goals.
Many people feel uncertain when deciding how to invest their retirement savings. Understanding the approaches of dollar-cost averaging and lump sum investing can clarify these decisions, reduce anxiety, and help you stay informed as you plan your financial future.
What Is Dollar-Cost Averaging?
How dollar-cost averaging works
Dollar-cost averaging is investing a fixed amount at regular intervals, regardless of market conditions. Rather than investing a large sum all at once, you contribute smaller amounts over time. This strategy automatically buys more shares when prices are low and fewer when prices are higher, potentially smoothing your average cost per share over time.
By following this systematic approach, you avoid trying to pick the “right” moment to invest. The goal is to reduce the emotional highs and lows of market volatility and execute your investment plan consistently, no matter what happens in the markets on any given day or month.
Common uses in retirement planning
Dollar-cost averaging is often used in retirement savings, such as contributing to a retirement account through payroll deductions. Many workplace retirement plans are set up to make regular, automatic contributions each pay period. This aligns naturally with dollar-cost averaging and helps you build your retirement savings steadily throughout your career.
This method can be especially useful for those who receive income regularly and want to invest as they earn, using the discipline and structure dollar-cost averaging provides.
What Does Lump Sum Investing Mean?
How lump sum investing functions
Lump sum investing involves putting a large amount of money into the market all at once. Instead of spreading contributions out, you invest a full portfolio amount immediately, based on your chosen asset allocation.
The rationale is that, historically, markets have trended upward over the long term. By investing sooner, your funds are exposed to potential market growth for longer, which can compound returns over time. However, lump sum investing carries its own emotional and market-related risks.
Situations where lump sum is chosen
People often choose lump sum investing when they have a significant amount of money available, such as from an inheritance, the sale of a home, or rolling over retirement savings when changing jobs. Some individuals may also choose lump sum investing to capitalize on perceived market opportunities or personal milestones.
This strategy may appeal to disciplined investors comfortable with temporary declines and who want to maximize time in the market rather than try to “wait out” short-term volatility.
How Do These Strategies Differ?
Process differences explained
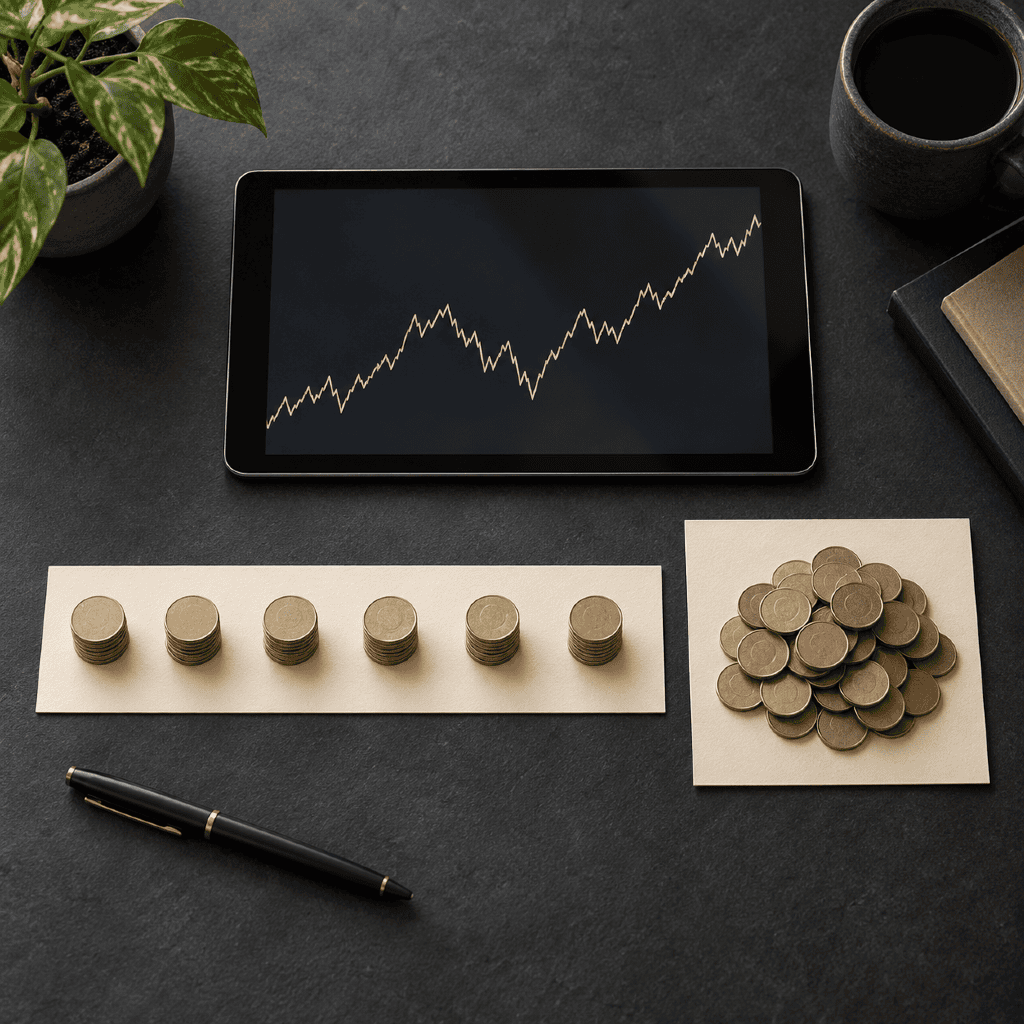
The main distinction between dollar-cost averaging and lump sum investing is timing and frequency. Dollar-cost averaging involves spreading investments evenly over set intervals, while lump sum investing deploys the entire investment at once.
With dollar-cost averaging, your investments are less sensitive to short-term price swings; you buy at different market levels. Lump sum investing exposes you more to the market’s immediate direction after you invest. If the market rises, your investment benefits fully from the start, but if it drops, the entire amount is impacted at once.
Potential impact on retirement goals
The strategy you choose can influence the growth of your retirement savings. Lump sum investing maximizes the time your funds spend in the market, which historically increases growth potential. Dollar-cost averaging may provide peace of mind by lessening the emotional stress of market fluctuations and may help reduce regret if the market drops after you invest.
Choosing between these methods requires balancing your desire for growth with your comfort in handling market ups and downs. Both strategies can support retirement savings, though their impact on long-term goals may differ based on market trends and investment timing.
What Are The Main Risks Involved?
Market timing risk considerations
Market timing risk refers to the challenge of predicting when to enter the market for optimal results. Lump sum investing carries the risk that you may invest just before a downturn, affecting your entire portfolio value from the outset. Dollar-cost averaging reduces the impact of poor market timing by spreading investments over time, though it may also dilute gains if markets rise quickly after your initial investment.
No strategy can fully eliminate the effects of market cycles. Both approaches carry risk, but they express it differently.
Potential emotional influences
Investor emotions can significantly impact decision-making. With lump sum investing, fear of losing a large amount to a sudden downturn may provoke second-guessing. Dollar-cost averaging, on the other hand, removes much of the emotional burden of trying to “time” investments but may lead to disappointment if the market rises consistently and missing out on larger gains.
Your emotional resilience and ability to stick to a plan should shape your investment approach.
Key Benefits of Each Approach
Advantages of gradual investing
Dollar-cost averaging provides structure and may help you invest without hesitation by removing the need to forecast short-term market movements. This can help avoid paralysis during volatile periods and encourage steady saving, supporting long-term discipline.
Gradual investing may also feel less daunting if you’re averse to risk, giving you a sense of control and reducing regret if markets are unpredictable.
Benefits of investing at once
Lump sum investing lets you put your money to work immediately. This lets your funds benefit from any potential market appreciation from day one. For those who can tolerate short-term volatility, this strategy can help maximize time in the market, an essential ingredient in long-term retirement planning.
Immediate investing also simplifies portfolio management because it requires fewer transaction decisions and may be less operationally complex than a multi-step plan.
Which Strategy Aligns With Your Goals?
Assessing personal comfort levels
When choosing a strategy, consider how you feel about market volatility, loss aversion, and investment discipline. If major swings in your portfolio’s value make you uneasy, or you’d rather not think about timing the market, dollar-cost averaging may feel more comfortable. If you are undeterred by short-term moves and focus on long-term growth potential, lump sum investing might suit you better.
Adapting strategies for retirement needs
Retirement planning is highly personal. Your preferences, timeframe, and income needs should all shape your investment strategy. You may also adjust your strategy as retirement approaches, favoring stability and predictability as the timeline shortens, or find that a blended approach balances comfort and opportunity.
Does One Strategy Suit All Retirees?
Considering diverse financial situations
Every retiree’s circumstances are unique. Income sources, savings history, health, and family needs all shape the most appropriate strategy. Some may be better served by gradual investing, while others may find a lump sum approach sensible.
Why individual preferences matter
Personal priorities, emotions, and previous experiences shape financial decisions. There is no one-size-fits-all answer, and what feels right for one person may not feel right for you. Being honest about your preferences and risk tolerance can make retirement planning more satisfying and sustainable.