Key Takeaways
- An emergency fund helps retirees manage unexpected expenses and supports financial stability in retirement.
- Ongoing monitoring, budgeting, and awareness of risks are essential to maintain your fund and peace of mind.
Being prepared for the unexpected is as important in retirement as it was during your working years. Even with careful planning, unforeseen costs can threaten your financial stability. By maintaining an emergency fund, you strengthen your ability to handle whatever surprises life brings in retirement.
Why Maintain an Emergency Fund in Retirement?
Protecting Retirement Security
When you transition into retirement, your income sources typically shift from employment earnings to structured streams such as Social Security benefits, pension payments, or withdrawals from personal savings. These income streams may offer stability, but unexpected expenses can still disrupt your financial confidence. Having an emergency fund acts as a buffer, protecting your planned lifestyle and preserving the longevity of your retirement resources.
An emergency fund, when well-managed, minimizes the need to sell long-term investments or alter your withdrawal schedule, which is especially important if markets are down or your income is fixed. Ultimately, your emergency reserve helps ensure that short-term financial surprises don’t become long-term setbacks.
Common Unexpected Costs in Retirement
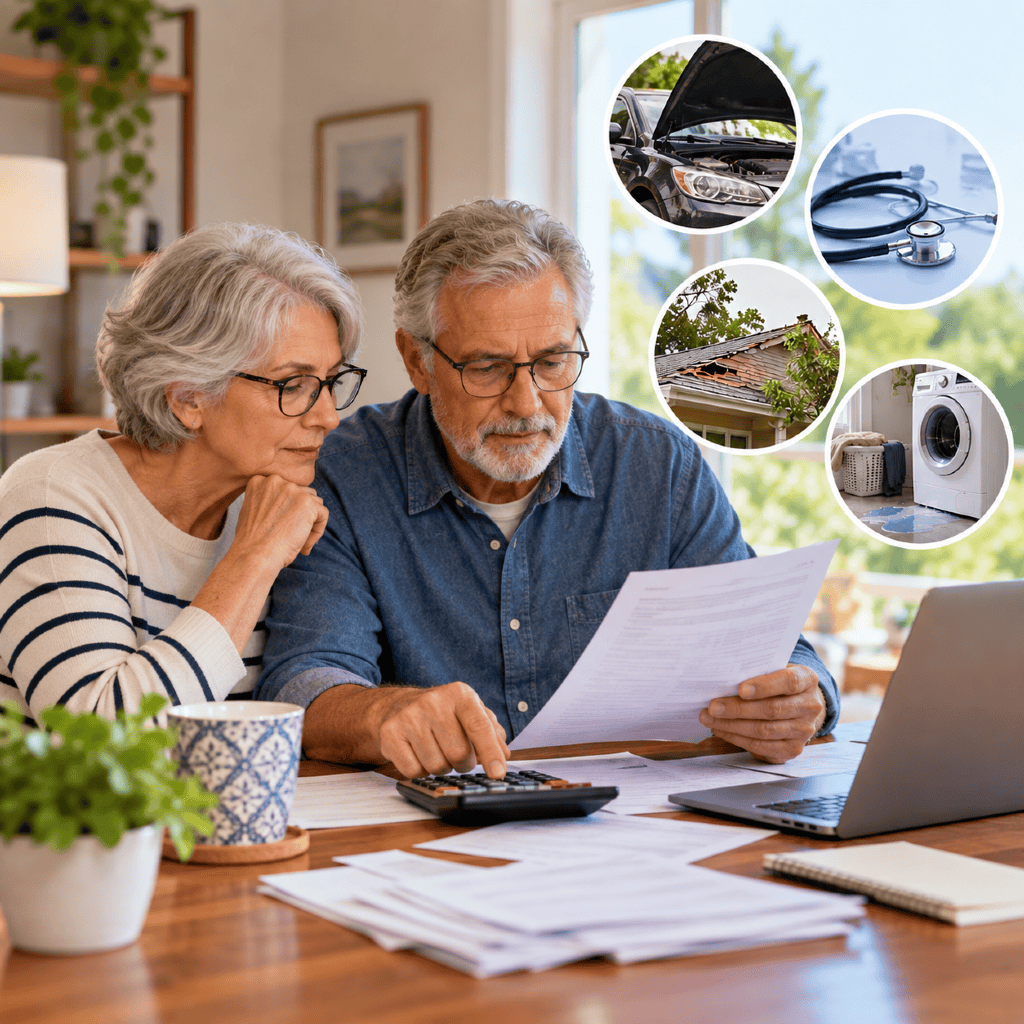
Retirement introduces new and sometimes unpredictable expenses. While your day-to-day spending might decrease as work-related costs fade, new categories—often out of your control—may arise. These include:
- Medical emergencies, such as hospitalizations or non-covered treatments
- Significant home or auto repairs
- Family support, like helping adult children or grandchildren in urgent situations
- Unanticipated travel, such as for family emergencies
- Expenses tied to local disasters (storms, fires, etc.)
Having a dedicated fund for these scenarios means you can address unforeseen needs without disrupting your retirement plans.
What Is an Emergency Fund for Retirees?
Definition and Purpose
An emergency fund is a reserve of liquid assets set aside specifically for rare, unpredictable financial events. For retirees, this fund is designed to fill financial gaps that may arise from sources outside your expected monthly or annual spending. It helps you avoid withdrawing from retirement accounts prematurely or at inopportune times, which could impact future income.
How Needs Change After Retiring
During your working years, income may be more flexible or easier to supplement in case of emergencies. In retirement, opportunities to increase earnings may be limited. This change means the safety net an emergency fund provides is even more important. Needs can also shift as health considerations, home maintenance, or changing family dynamics evolve with age. By reassessing the fund’s size and accessibility as your situation changes, you stay better prepared.
How Can Retirees Manage Unexpected Expenses?
Budgeting Approaches
A thoughtful, realistic retirement budget is your first line of defense. Budgeting in retirement goes beyond tracking routine expenses; it includes:
- Allocating a portion of assets to your emergency fund
- Reviewing anticipated costs annually
- Building in padding for rising healthcare or lifestyle changes
You may find value in grouping spending into needs, wants, and wishes, setting priorities, and ensuring nonnegotiable expenses have a secure funding source. Including line items for unpredictable events, even in broad estimates, encourages discipline and readiness.
Flexible Spending Strategies
Since not every emergency can be predicted, flexibility is critical. Retirees benefit from monitoring cash flow and keeping certain assets easily accessible, ensuring funds can be tapped when needed. You can:
- Designate a specific savings or money market account as your emergency stash
- Periodically evaluate spending categories to identify where adjustments could be made should an emergency arise
- Practice periodic “stress tests,” imagining various what-if events and how you’d cover them (without disrupting necessary expenses or income planning)
Flexibility also means knowing which discretionary expenses could be put on hold if a larger withdrawal becomes necessary.
Steps to Maintain an Emergency Fund
Monitoring Withdrawals
Regularly tracking withdrawals from your emergency fund is vital for its long-term effectiveness. By keeping a simple log of why and when you dip into this reserve, you gain insights into patterns and can better predict future needs. This monitoring can also help you avoid repeat or preventable expenses and strengthen your overall budgeting discipline.
Replenishing After Use
Using your emergency fund is not a failure—it’s what the money is there for. The crucial step afterward is restoring the balance over time. This might involve:
- Temporarily reducing discretionary spending
- Scheduling small, regular transfers back into the fund
- Adjusting future income planning, such as modestly reducing planned annual withdrawals for a period
By making fund replenishment a defined goal, it remains ready for the next unforeseen need.
What Can Jeopardize an Emergency Fund?
Lifestyle Inflation
After retirement, it’s understandable to enjoy the rewards of your hard work. However, gradually increasing your standard of living (lifestyle inflation) can quietly erode your emergency buffer. Regularly reviewing your spending habits and reminding yourself of the fund’s purpose helps guard against this silent risk.
Unplanned Large Expenses
Occasionally, expenses may far exceed what was anticipated—such as a severe health event or major home repair. If your fund is depleted by a single event, it’s not just the immediate cost but also the opportunity cost of lacking reserves for future needs. Anticipating the possibility of infrequent, substantial costs—and maintaining awareness of how quickly the fund can be rebuilt—protects your broader financial picture.
Lessons from Real-Life Scenarios
Navigating Medical Emergencies
Consider a retiree couple who faced a sudden health crisis requiring urgent, out-of-network care. Because they had kept a portion of their assets liquid and earmarked for precisely these occasions, they managed short-term costs without interrupting their regular retirement income flows. Afterward, they revised their healthcare assumptions and reallocated assets to rebuild their reserve.
Handling Home Repairs
Another common story: a retiree encounters a costly plumbing failure during winter. With a separate emergency account, the repair was handled promptly, preventing further damage and costs. Reflecting on the experience led to a review of home maintenance budgeting and reaffirmed the value of keeping emergency savings distinct from other assets.