Key Takeaways
- Understanding both Medicare IRMAA and Part B adjustments is essential for effective retirement income planning.
- Staying informed about policy changes and income thresholds can help you better manage your future Medicare costs.
When planning for retirement, anticipating your future Medicare costs is crucial. Income-related adjustments such as IRMAA and Part B adjustments can affect your healthcare expenses, making it important to understand how these two concepts work and what they mean for your long-term financial plans.
What Is Medicare IRMAA?
Explanation of IRMAA
The Income-Related Monthly Adjustment Amount, or IRMAA, is an additional surcharge that some individuals pay for their Medicare Part B and Part D coverage. This surcharge is calculated based on your reported income from previous years. IRMAA aims to align contributions more closely with the financial capacity of each retiree.
Who Is Affected by IRMAA?
Not everyone enrolled in Medicare pays IRMAA. If your income—typically determined from your tax return two years prior—exceeds specific thresholds, you may pay a higher premium for Medicare Part B and Part D. This means IRMAA generally impacts higher-income retirees but can also apply in specific one-time situations when income spikes.
How IRMAA Is Calculated
IRMAA amounts are set using income brackets established by federal policy. Your modified adjusted gross income (MAGI) is used to determine which bracket you fall into. Each bracket corresponds to a different surcharge amount. These brackets and thresholds are subject to change, so staying updated with the latest guidelines is important for accurate planning.
What Are Medicare Part B Adjustments?
Overview of Part B Adjustments
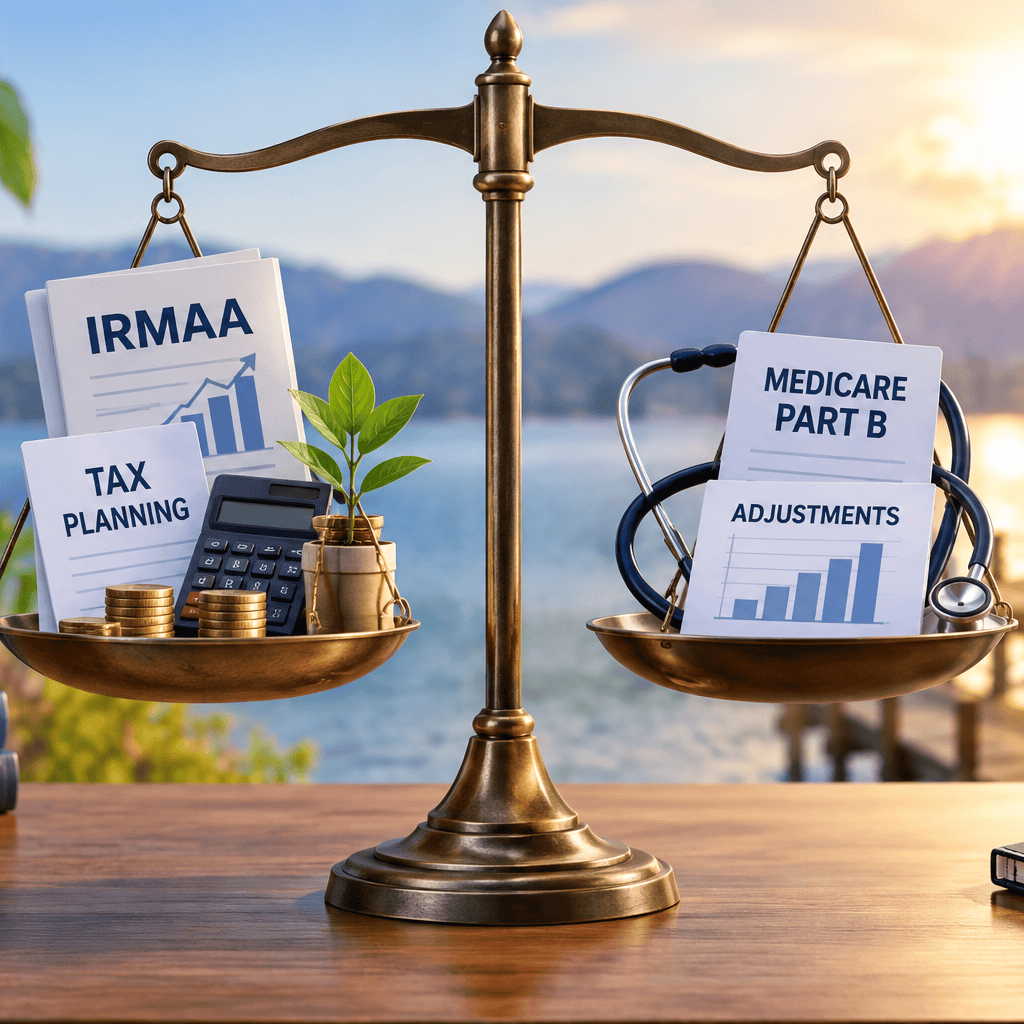
Medicare Part B adjustments refer to changes in your standard Part B premium that can occur due to several factors, such as annual government re-evaluations, income changes, or legislative updates. While IRMAA is a specific kind of income-related adjustment, “Part B adjustments” can include both routine annual updates and individual circumstances that result in modifications to your premiums.
Why Do Adjustments Occur?
Adjustments to Part B premiums occur for various reasons. The government regularly updates premiums based on program costs, which can change due to healthcare expenses, ongoing demographic shifts, and federal policy decisions. Additionally, adjustments can result from personal income changes or eligibility updates, affecting what you pay in future years.
Who Experiences These Adjustments?
Almost all Medicare beneficiaries may see routine annual adjustments in their Part B premiums as the standard rate changes over time. Only those whose incomes trigger IRMAA experience the income-related adjustment portion. Still, understanding both the general and specific types of adjustments is central to retirement planning.
How Do IRMAA and Part B Adjustments Differ?
Eligibility Differences
IRMAA applies specifically to those whose income, as reported two years prior, exceeds federal thresholds. Standard Part B adjustments apply to all enrollees, regardless of income, as annual premiums are updated universally. So, you could see a Part B adjustment even if you never pay IRMAA.
Calculation Method Differences
While standard Part B premium adjustments are determined by nationwide program costs and government policy, IRMAA is calculated using more personalized data, relying on your specific income bracket based on MAGI. This individualized approach means IRMAA can affect some retirees much more than others, depending on their financial circumstances.
Timing and Notification
Standard Part B premium changes generally take effect at the beginning of each year, following the release of new rates by the federal government. IRMAA surcharges are applied after the Social Security Administration reviews income tax records—typically from two years ago—and sends you an official notice if you owe the additional surcharge. It’s important to monitor your mail and statements annually to track both types of changes.
What Are the Retirement Implications?
Impact on Retirement Income Planning
Both IRMAA and Part B adjustments play a significant role in shaping your retirement income planning. Unexpected surcharges or premium hikes can erode your discretionary spending or require reallocation from other parts of your retirement budget. Factoring these potential costs into your long-term plan helps you avoid surprises and supports a more sustainable income strategy.
Considerations for Budgeting Healthcare Costs
Because IRMAA is income-based, withdrawals from certain retirement accounts can unintentionally increase your Medicare costs if they bump you into a higher threshold. Planning income streams and timing distributions with awareness of how they influence IRMAA exposure is a common retirement consideration. At the same time, staying up to date on annual premium announcements helps you revise your budget and funding strategies as needed.
Effect on Medicare Enrollment Decisions
Some retirees consider their income trajectory and expected premium adjustments when making Medicare enrollment decisions. For example, delaying or timing Social Security or tax-advantaged withdrawals may affect your exposure to IRMAA. A clear understanding of both standard and income-related adjustments enhances your decision-making confidence as you navigate Medicare enrollment windows.
Pros and Cons of IRMAA Tax Planning
Potential Benefits of Tax Planning
Effective tax planning might help you manage exposure to IRMAA. By spreading retirement account withdrawals, utilizing tax-managed investment strategies, or coordinating distributions among taxable and non-taxable accounts, you can sometimes reduce the risk of falling into a higher Medicare income bracket. This helps in making your healthcare costs more predictable.
Drawbacks and Limitations
While tax planning may help you address IRMAA, there are limitations. Changes to tax law, unexpected income, or one-time financial events can quickly shift your standing in the Medicare brackets. In addition, strategic planning must not focus solely on IRMAA to the exclusion of other retirement goals like portfolio growth, liquidity, or legacy planning.
Common Misconceptions
A common misconception is that IRMAA is avoidable with simple planning, but income-related adjustments are complex, interact with broader tax and retirement strategies, and may not be entirely addressed with one approach. Additionally, some believe only high earners need to be concerned, yet one-time capital gains, sales, or conversions can trigger an IRMAA adjustment.
When Should You Consider Each Strategy?
Assessing Personal Retirement Situations
Consider your broader retirement goals, expected income sources, and probability of future income spikes when evaluating Medicare planning strategies. Those with variable income—such as retirees who draw from different accounts—should pay particular attention to how their actions might impact both IRMAA and Part B adjustments.
Timing Considerations for Each Approach
Timing matters: since IRMAA is based on income from two years prior, it’s helpful to plan your withdrawals and income events with enough lead time. For standard Part B premium increases, monitor announcements and adjust your budget before the new rates take effect each year.
Long-Term Planning Awareness
Long-term awareness involves monitoring changes in policies, adjusting your personal plan as your financial situation evolves, and re-evaluating your strategies regularly. This steady, proactive approach helps reduce the risk of facing unexpected Medicare surcharges in future retirement years.
How Can You Stay Informed About Changes?
Resources for Medicare Policy Updates
To keep up with updated standards and surcharges, use official sources like the Medicare website and Social Security Administration notices. These resources provide reliable, current information about premiums, adjustment thresholds, and new regulations.
Tips for Monitoring Income Threshold Changes
Income thresholds for IRMAA and standard Part B adjustments can change year to year. Make a habit of reviewing policy updates each fall so you can incorporate changes into your year-end and long-term planning. Digital tools and retirement news outlets can be helpful for receiving timely updates.
Staying Prepared for Adjustment Notices
Always review correspondence from Social Security and Medicare. Adjustment notifications—especially for IRMAA—typically outline reasons, calculation methods, and any response deadlines. Being responsive can help you address potential errors and make adjustments to your retirement plan promptly.