Key Takeaways
- Asset allocation is a core principle that helps balance income, security, and risk in retirement planning.
- Regular review and adjustment of your asset mix can better align your portfolio with changing life events and income needs.
Did you know that your approach to asset allocation can have as much impact on retirement security as the amount you save? Understanding asset allocation is essential for shaping sustainable retirement income, managing risk, and achieving peace of mind throughout your retirement years.
What Is Asset Allocation?
Definition and core principles
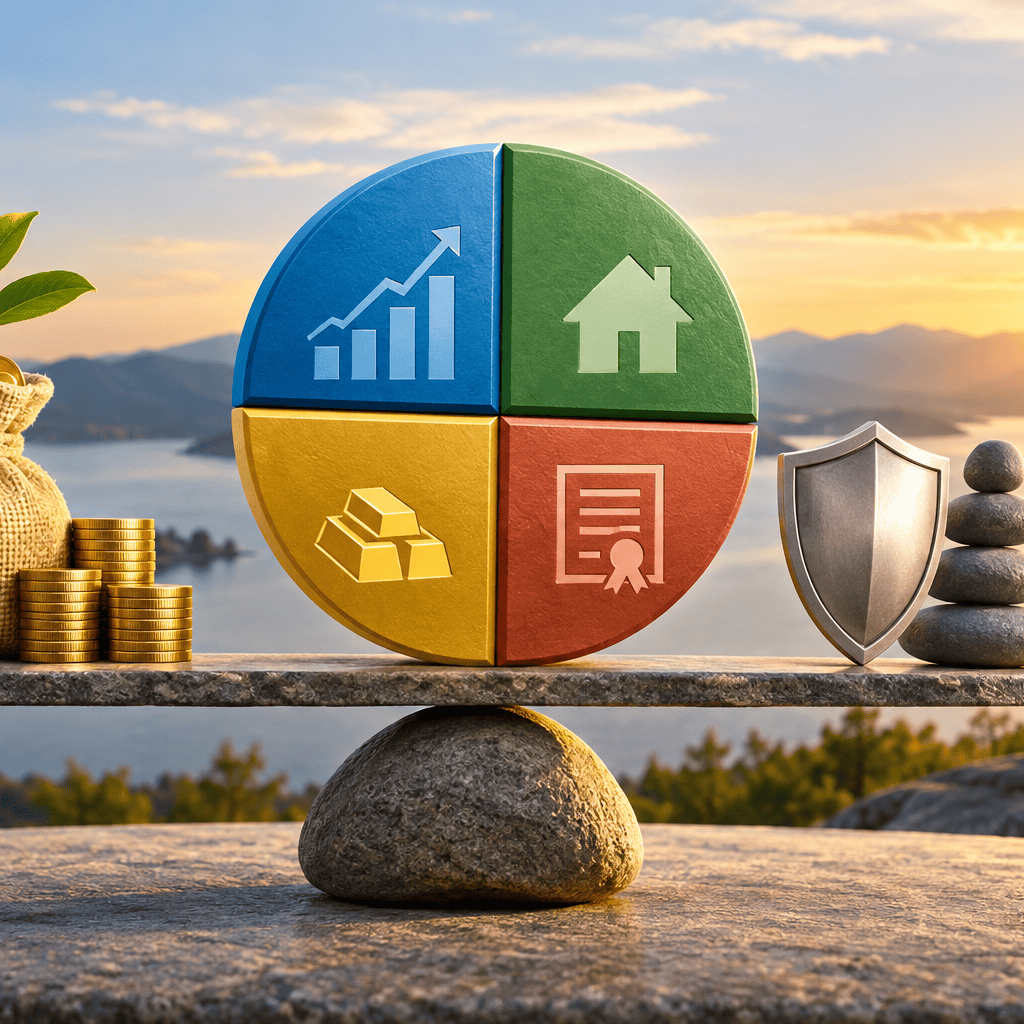
Asset allocation is the process of dividing your retirement savings among different asset classes—such as stocks, bonds, and cash alternatives. The core principle behind asset allocation is diversification: by mixing various asset types, you’re less exposed to the performance of any single investment or market. This approach aims to smooth the ups and downs of your portfolio over time, favoring stability and resilience.
Types of assets in retirement portfolios
Retirement portfolios commonly include:
- Equities (stocks): These provide potential for long-term growth, helping your savings keep pace with inflation.
- Fixed income (bonds): Bonds typically offer steady income and may help reduce overall portfolio fluctuations.
- Cash and cash equivalents: These are highly liquid and can help meet short-term spending needs.
- Other alternatives: Some portfolios may include real estate or commodities, adding further diversification.
The mix of these assets defines your allocation strategy and impacts how your portfolio responds to market conditions.
Why Does Asset Allocation Matter in Retirement?
Impact on retirement income sustainability
The right asset allocation can help ensure that your retirement income lasts as long as you need it. By blending growth-oriented assets with more stable income-producing ones, you can create a portfolio designed to generate income while managing the risk of running out of funds prematurely.
Role in long-term security
Long-term financial security in retirement is closely linked to how you split your investments. Diversifying assets can help minimize the effects of market downturns and preserve your ability to meet retirement goals, even when markets are volatile. With a strategic mix, you are better able to weather economic shifts and sustain your standard of living.
How Does Asset Allocation Balance Risk?
Managing market ups and downs
Markets naturally rise and fall, sometimes unpredictably. Asset allocation works to buffer your portfolio from drastic swings by spreading exposure across various investment types. For example, in periods when stocks decline, bonds or cash may hold steady or even increase in value. This blend helps maintain steady ground when markets fluctuate.
Reducing the impact of inflation
Inflation can erode purchasing power over time. Allocating a portion of your retirement savings to assets with growth potential—like stocks—can help offset inflation’s effects. Balancing these with more stable investments helps ensure that your income can keep up with future costs.
What Are Common Asset Allocation Strategies?
Conservative, balanced, and growth approaches
- Conservative: Prioritizes capital preservation and income, with a larger share in bonds and cash. Suitable if you have a lower risk tolerance or are focused on near-term withdrawals.
- Balanced: Seeks a mix of growth and income, often with a 50/50 or 60/40 split between equities and fixed income. This approach balances moderate risk and return needs.
- Growth: Focuses on stocks to pursue higher potential returns, with a smaller share in bonds or cash. More appropriate when you have a longer time horizon or higher risk tolerance.
Adjusting allocation as needs change
Your ideal asset mix can shift as you move from accumulation to spending in retirement. Gradually shifting toward a more conservative allocation can reduce volatility as you begin drawing regular income. The key is revisiting your strategy as your goals, time frame, and comfort with risk evolve.
How Can Asset Allocation Support Income Needs?
Generating income from investments
Asset allocation directly supports your ability to pull income from your investments. By including both growth (equities) and income-producing assets (bonds and cash equivalents), you create the potential for both stability and continued income throughout retirement.
Providing flexibility for withdrawals
A diversified allocation allows you to be strategic about from which assets you make withdrawals. During market downturns, you might draw from more stable assets. In more favorable conditions, you can tap growth assets. This flexibility can help preserve portfolio value over time.
What Should Retirees Consider When Allocating Assets?
Evaluating personal risk tolerance
Before finalizing any asset allocation, it’s important to assess how much market ups and downs you can comfortably accept. Consider your other income sources, planned spending, and how you tend to react in volatile markets. Your risk tolerance should guide how aggressively or conservatively you allocate your savings.
Aligning allocation with retirement goals
Define your key retirement objectives—such as desired lifestyle, legacy plans, and anticipated expenses. Then, tailor your allocation so it aligns with these goals and your required timeline. Periodic reassessment ensures your investment mix remains supportive as circumstances change.
Are There Risks of Not Adjusting Asset Allocation?
Potential downsides of static allocation
A set-it-and-forget-it approach to allocation can expose you to unnecessary risks or missed opportunities. Over time, shifting markets may cause your portfolio to drift away from your intended balance, increasing your exposure to certain assets and reducing diversification benefits.
How changing needs affect investment mix
As your lifestyle, health status, or family circumstances shift, your need for income or protection might change. Failing to update your asset allocation can mean your investments no longer serve your actual needs, making your plan less effective at providing reliable retirement income and security.
How Often Should Asset Allocation Be Reviewed?
Life events that may prompt a review
Major milestones like retirement, the sale of a home, or changes in health are all moments to revisit your asset mix. Even absent major events, aim to review your allocation at least every year, checking for portfolio drift and realigning as needed.
Practical tips for staying on track
- Set calendar reminders to review at regular intervals (annual or semiannual works well)
- Rebalance when your asset mix drifts significantly from your targets
- Stay focused on your long-term objectives rather than reacting to short-term market swings
Can Asset Allocation Address Longevity Concerns?
Balancing present and future needs
Asset allocation helps you manage the challenge of funding a retirement that could last for decades. Allocating for both immediate income and long-term growth means you’re less likely to outlive your resources or face shortfalls later on.
Supporting income over a long retirement
A thoughtfully diversified portfolio can support ongoing income needs, absorbing inflation and market shifts over time. This strategic mix offers a pathway to financial stability throughout all chapters of retirement, even as circumstances evolve.